Product Launch
July 2026
Astok Credit Engine V2: Real-time On-Chain Risk Modeling is Live
Introducing our next-generation credit risk oracle, connecting live payment processing pipelines with on-chain credit generation.
4 min readRead article
Built for embedded commerce & decentralized finance
From one-off lending relationships to long-term credit lifecycle management. Rebuild credit infrastructure via real-time transaction data and automated execution.
Connect store data streams (Shopify, Stripe, or POS) to instantly calibrate initial credit limits. Avoid sluggish manual auditing.
< 5 Min Approval
“Shifting merchants from a traditional one-off loan to building a long-term credit relationship within the Astok system.”
We understand the relentless pressures of rent, inventory procurement, and payroll. Our data-driven credit model provides a safer, fully transparent, stress-free financing path.
Borrow HK$10,000 with a daily sweep of just ~HK$33. Effortless micro-adjustments keep your cash flow extremely liquid.
Select any amount between HK$50,000 and HK$300,000. Perfect for stock prep, peak season campaigns, rent deposits, or renovations.
Credit assessment built strictly on storefront telemetries. Zero property or personal asset liens required, protecting your private wealth.
Submit storefront connections securely. Our automated systems analyze immediately with fast approvals in 30 minutes.
Say goodbye to rigid, compounding interest schedules and static collateral requirements. Underwrite custom digital credit lines matched directly to SaaS telemetry and POS payment streams.
From fast-growing vertical SaaS platforms to top tier digital aggregators, software operators use Astok to expand their product offerings with embedded payments, automated risk calibration, and programmatic credit pipelines.
Hello, Daybreak Yoga 👋
You're pre-qualified for up to $37,000 in financing
AVAILABLE FOR PAYOUT
$820.56
Action Required
To make sure your credit line remains active, verify your physical business address.
import { AstokConnect } from '@astok/sdk';

const astok = new AstokConnect('pk_live_...');

// Render pre-qualified funding promo widget
astok.create('capital-financing-promotion', {
  targetId: '#capital-promo-container',
  maxLimit: 37000,
  currency: 'USD'
});Launch and scale credit products with minimal operational overhead. Use our modular UI widgets, custom smart contract blueprints, and ready-to-use API endpoints.
Read the integration guideMonetize your platform's merchant transactions. Earn native revenue shares from interest spreads, transaction routing fees, and dynamic credit origination commissions.
Explore monetization modelsStay ahead of credit volatility with multi-source risk controls. Real-time data feeds, automatic repayments, and decentralized pools protect your capital from localized shocks.
View our risk frameworkIntroducing our next-generation credit risk oracle, connecting live payment processing pipelines with on-chain credit generation.
Our new institutional credit channel bridges traditional capital providers with high-velocity digital commerce, creating stable high-yield pipelines.
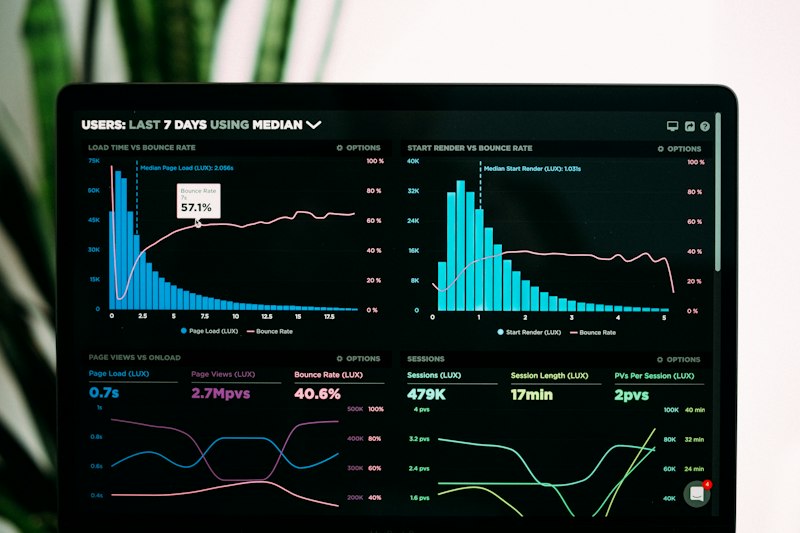
A mathematical breakdown of how transparency and immediate cryptographic proof of repayments minimize risk premiums for global lending desks.
MCA Education
An MCA is not a traditional loan — it is flexible financing tied to your daily revenue. The most common questions, organised into basics and advanced groups.
An MCA is not a traditional bank loan but a purchase-and-sale agreement on future revenue. The funding provider (such as Astok) buys a portion of the merchant's future card, e-payment or store revenue upfront at a discount. The merchant receives immediate working capital and agrees to an automatic deduction — a fixed percentage (the split rate) of each day's revenue — until the purchased amount is fully settled.
Traditional loans carry fixed repayment terms, fixed monthly instalments, and usually compound interest and APR calculations — the monthly burden stays the same even when business slows. An MCA has no fixed repayment term: the repayment amount follows the merchant's actual daily revenue. In peak seasons repayments accelerate; in quieter periods they fall in step with revenue, greatly easing the merchant's cashflow pressure.
MCAs do not charge annualised interest. Instead they use a factor rate (typically between 1.08 and 1.18) — a fixed multiplier. For example, a merchant approved for an HK$200,000 advance at a 1.12x factor rate will repay a fixed HK$224,000 in total (HK$200,000 × 1.12). That amount is locked in at signing and never accrues additional penalties or compounding, no matter how long repayment takes.
The split rate is the percentage of each day's settlement automatically routed to the funder (typically between 5% and 15%). For example, at a 10% split rate, on a day the store collects HK$20,000 through e-payments, HK$2,000 (10%) is automatically deducted toward settling the advance, while the remaining HK$18,000 is paid out to the merchant's regular bank account.
Expected repayment days = (advance amount × factor rate) ÷ (average daily revenue × split rate). For example: an HK$100,000 advance at a 1.10 factor rate means HK$110,000 total repayment; at HK$10,000 average daily revenue with a 10% split rate (HK$1,000 per day), full settlement takes about 110 days. Settlement speed tracks actual sales exactly.
Astok securely connects to a merchant's POS systems, e-payment gateways (such as Stripe, Octopus and PayMe) and public Food and Environmental Hygiene Department (FEHD) data through Open APIs. Our AI risk engine automatically analyses twelve months of revenue stability, refund rates, customer retention patterns, seasonal fluctuations and remaining lease term. Without stacks of collateral documents, it computes a tailored factor rate and maximum safe credit line within seconds.
Because MCA repayment follows "no revenue, no repayment", a merchant who closes for renovation or an emergency and takes HK$0 that day owes HK$0 that day. This sits entirely within the contract's terms: no traditional loan default penalties, and no impact on the merchant's personal credit assessment with banks (TU report) — a true partnership in which funder and merchant share both feast and famine.
Adjust the four values below to instantly estimate total repayment, the daily split amount and the expected settlement days.
Our vision & capability
We are an embedded finance infrastructure provider built natively on blockchain technology, dedicated to seamlessly integrating merchant financing capabilities into SaaS platform ecosystems.
About Astok
Astok is a premier global FinTech pioneer leading the convergence of web3 liquidity and digital-native merchant commerce. Under the banner of “Let Credit Flow On Chain”, we build programmatic infrastructure that empowers software platforms to convert transactional telemetry into low-latency, yield-bearing assets.
Partner with us
Our regional integration teams are ready to help SaaS platforms, marketplaces, and POS systems build high-velocity embedded credit services globally.
Our platform solution architects generally respond to certified API integrations in < 2 hours.